Managing money becomes easier when you have a simple system to decide where your income should go. One popular approach is the 50/30/20 budget rule, which divides your after-tax income into three broad categories: needs, wants and savings or debt repayment.
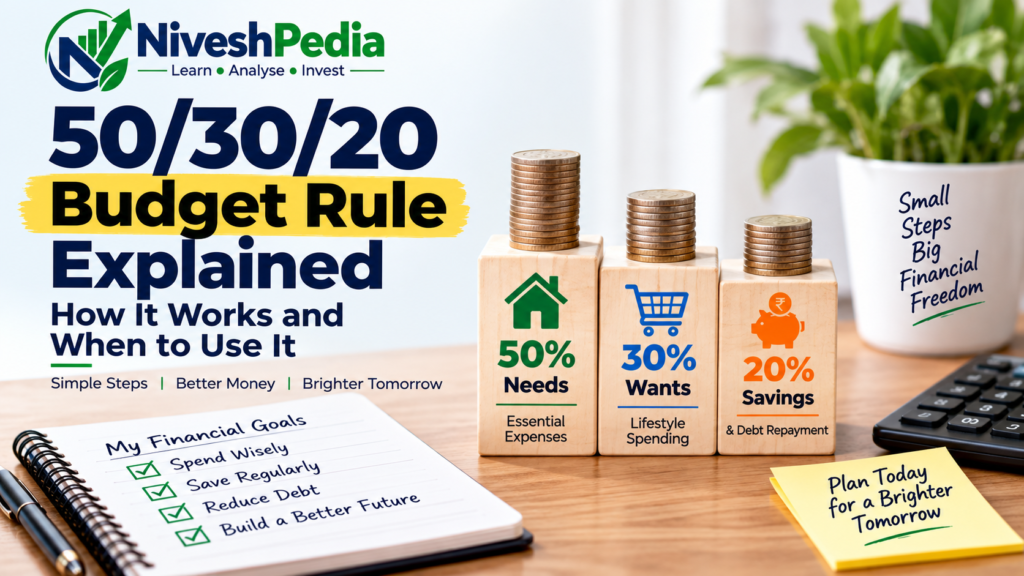
The idea is simple: roughly 50% of your income goes toward needs, 30% toward wants, and 20% toward savings and financial goals.
However, the 50/30/20 rule is not a strict formula that works perfectly for everyone. Your income, living costs, family responsibilities, debt, financial goals and location can all affect how much you can reasonably allocate to each category.
In this guide, you’ll learn how the 50/30/20 budget rule works, what belongs in each category, how to calculate it with an example, and when you may need to adjust the percentages.
Table of Contents
- What Is the 50/30/20 Budget Rule?
- How Does the 50/30/20 Rule Work?
- 50/30/20 Budget Rule Example
- How to Calculate Your 50/30/20 Budget
- What If Your Needs Are More Than 50%?
- Should You Follow the 50/30/20 Rule Exactly?
- 50/30/20 Rule for Beginners
- Common Mistakes When Using the 50/30/20 Rule
- Benefits of the 50/30/20 Budget Rule
- Limitations of the 50/30/20 Rule
- How to Make the 50/30/20 Rule Work Better
- 50/30/20 Budget Rule vs. a Traditional Budget
- How the 50/30/20 Rule Fits Into Personal Finance
- Frequently Asked Questions
- Key Takeaways
What Is the 50/30/20 Budget Rule?
The 50/30/20 budget rule is a budgeting method that divides your monthly after-tax income into three major categories:
- 50% for needs
- 30% for wants
- 20% for savings and debt repayment
The purpose is to create a simple framework that helps you balance your essential expenses, lifestyle spending and financial goals.
For example, if your monthly take-home income is ₹50,000, the basic calculation would look like this:
| Category | Percentage | Amount |
|---|---|---|
| Needs | 50% | ₹25,000 |
| Wants | 30% | ₹15,000 |
| Savings & debt repayment | 20% | ₹10,000 |
| Total | 100% | ₹50,000 |
These percentages are guidelines rather than fixed requirements. If your essential expenses are higher than 50%, you may need to adjust the allocation.
How Does the 50/30/20 Rule Work?
The rule works by assigning every major expense to one of three categories.
1. 50% for Needs
Needs are expenses that are important for your basic living and financial obligations.
Examples can include:
- Rent or home loan payments
- Groceries
- Electricity and other essential utilities
- Basic transportation
- Essential medical expenses
- Insurance premiums
- Minimum loan or debt payments
- School or education-related essential expenses
The exact definition of a “need” can vary from person to person.
For example, transportation may be a necessity if you need to travel to work, while an expensive upgrade to a premium vehicle may be more of a lifestyle choice.
The goal is to identify expenses that you genuinely need rather than automatically treating every regular expense as essential.
2. 30% for Wants
Wants are expenses that make life more enjoyable but are not generally essential for basic living.
Examples include:
- Restaurant meals
- Movies and entertainment
- Shopping for non-essential items
- Streaming subscriptions
- Hobbies
- Vacations
- Premium gadgets
- Non-essential upgrades
- Leisure activities
Wants are not necessarily bad expenses.
A realistic budget should leave some room for enjoyment. The purpose of budgeting is not to eliminate every enjoyable activity but to make sure lifestyle spending remains manageable.
3. 20% for Savings and Debt Repayment
The final 20% is directed toward improving your financial position.
Depending on your situation, this category can include:
- Emergency fund contributions
- Retirement savings
- Long-term savings
- Investments
- Additional debt repayment
- Other important financial goals
For someone building an emergency fund, a portion of this money may first be directed toward that goal.
After establishing an adequate emergency reserve, you may allocate more toward longer-term financial goals depending on your circumstances.
50/30/20 Budget Rule Example
Let’s take a practical example.
Suppose your monthly take-home income is ₹60,000.
Using the basic 50/30/20 framework:
Needs — 50%
₹60,000 × 50% = ₹30,000
This could cover expenses such as:
- Rent
- Groceries
- Utilities
- Transportation
- Essential insurance
- Minimum debt payments
Wants — 30%
₹60,000 × 30% = ₹18,000
This could include:
- Eating out
- Entertainment
- Shopping
- Hobbies
- Travel
- Subscriptions
Savings and Debt Repayment — 20%
₹60,000 × 20% = ₹12,000
This could be used for:
- Emergency savings
- Investments
- Retirement planning
- Additional debt repayment
- Other financial goals
Again, these are simply example allocations. Your actual numbers may need to be different.
How to Calculate Your 50/30/20 Budget
You can calculate the rule in a few simple steps.
Step 1: Find Your Monthly Take-Home Income
Start with the money you actually receive after applicable deductions.
For example:
Monthly take-home income = ₹50,000
If your income changes from month to month, you may want to use a conservative average rather than assuming your highest monthly income.
Step 2: Calculate 50% for Needs
Multiply your take-home income by 0.50.
₹50,000 × 0.50 = ₹25,000
Your approximate needs budget would therefore be ₹25,000.
Step 3: Calculate 30% for Wants
Multiply your income by 0.30.
₹50,000 × 0.30 = ₹15,000
Your approximate wants budget would be ₹15,000.
Step 4: Calculate 20% for Savings and Debt
Multiply your income by 0.20.
₹50,000 × 0.20 = ₹10,000
You would aim to direct around ₹10,000 toward savings, investments or additional debt repayment.
What If Your Needs Are More Than 50%?
This is one of the most important things to understand about the 50/30/20 rule.
You should not force your expenses into these percentages if they don’t reflect your financial reality.
For example, suppose your take-home income is ₹40,000 but your essential expenses are already ₹25,000.
Your needs would represent:
₹25,000 ÷ ₹40,000 × 100 = 62.5%
That doesn’t mean your budget has failed.
It simply means the standard 50/30/20 framework may not currently fit your circumstances.
You could temporarily use a different allocation, such as:
- 60% needs
- 20% wants
- 20% savings
Or even:
- 65% needs
- 15% wants
- 20% savings
The right budget is one you can realistically maintain.
Should You Follow the 50/30/20 Rule Exactly?
No.
Think of the 50/30/20 rule as a starting framework, not a financial law.
Your ideal budget may look different because of factors such as:
- High housing costs
- Family responsibilities
- Existing debt
- Irregular income
- Medical expenses
- Education expenses
- Short-term financial goals
- Retirement goals
- Different stages of life
Someone living in a lower-cost area may have very different expenses from someone living in a major city.
Similarly, a person with significant debt may need to prioritize debt repayment over discretionary spending.
50/30/20 Rule for Beginners
If you’re completely new to budgeting, don’t worry about getting the percentages perfect immediately.
Start with these steps:
1. Track your income
Know exactly how much money you receive each month.
2. Track your expenses
Record your spending for at least one month so you understand where your money is going.
3. Separate needs and wants
Look at your expenses and decide which ones are essential and which ones are discretionary.
4. Check your savings
See how much you’re currently saving.
5. Compare your numbers with 50/30/20
Use the rule as a reference point.
6. Adjust your budget
Make changes that are realistic for your financial situation.
Common Mistakes When Using the 50/30/20 Rule
Mistake 1: Treating the percentages as strict rules
The percentages are guidelines. Your personal circumstances matter more than following an exact formula.
Mistake 2: Calling every expense a need
Some expenses may feel necessary simply because you’re accustomed to them.
Review your spending carefully.
Mistake 3: Ignoring debt
Minimum debt payments may fall under needs, while additional repayment can be part of your savings/debt category.
Understand your own debt obligations before deciding how much you can allocate elsewhere.
Mistake 4: Forgetting irregular expenses
Annual insurance payments, school expenses, repairs and other occasional costs can disrupt a monthly budget if you don’t plan for them.
Consider setting aside money regularly for predictable irregular expenses.
Mistake 5: Cutting all wants
A budget that leaves no room for enjoyment may be difficult to maintain.
The goal is balance, not extreme restriction.
Benefits of the 50/30/20 Budget Rule
The method has several potential advantages for beginners.
Simple to understand
You don’t need a complicated budgeting system to get started.
Creates balance
It encourages you to consider essential expenses, lifestyle spending and financial goals together.
Encourages saving
Having a specific portion dedicated to savings can help make saving a regular habit.
Flexible
You can adjust the percentages according to your circumstances.
Helps identify spending problems
If your wants consistently consume a large part of your income, the framework can help you recognize the issue.
Limitations of the 50/30/20 Rule
The rule also has limitations.
It may not work neatly for people with:
- Very low income
- Very high housing costs
- Large debt obligations
- Irregular income
- Significant family responsibilities
- Major short-term financial goals
For these situations, a customized budget may be more appropriate.
The most useful budget is not necessarily the one that follows a popular formula. It is the one that helps you manage your money consistently while working toward your financial goals.
How to Make the 50/30/20 Rule Work Better
You can make the framework more useful by combining it with regular expense tracking.
For example:
Track → Categorize → Review → Adjust → Repeat
At the end of each month, review:
- How much did I earn?
- How much did I spend?
- How much did I save?
- Did my needs exceed my target?
- Did I spend too much on wants?
- Did I make progress toward my financial goals?
You can then adjust the following month’s budget.
A budget is not something you create once and forget. Your income and expenses can change over time, so your budget should change with them.
50/30/20 Budget Rule vs. a Traditional Budget
A traditional budget may track individual expense categories in much greater detail.
For example:
- Rent
- Groceries
- Electricity
- Transportation
- Entertainment
- Shopping
- Investments
- Insurance
The 50/30/20 rule groups many of these expenses into three broader categories.
This makes it easier for beginners to understand the overall balance of their spending without creating dozens of categories.
A detailed budget may be better for someone who wants close control over every expense, while the 50/30/20 approach can be a useful starting point for someone who wants simplicity.
How the 50/30/20 Rule Fits Into Personal Finance
Budgeting is only one part of personal finance.
A strong personal finance approach can also involve:
- Managing income
- Controlling expenses
- Building an emergency fund
- Managing debt
- Saving for important goals
- Investing according to your circumstances
- Having appropriate financial protection
- Planning for the future
If you’re new to these concepts, you can first understand what personal finance means and then build a practical monthly budget.
Frequently Asked Questions
Is the 50/30/20 rule suitable for everyone?
No. It is a general budgeting framework rather than a rule that must work for everyone. Your income, expenses, debt and financial goals may require different percentages.
Does the 50/30/20 rule use gross income or take-home income?
The framework is generally applied to after-tax or take-home income, because that is the money available for your monthly spending and financial goals.
What counts as a need in the 50/30/20 rule?
Needs are essential expenses such as housing, food, basic utilities, necessary transportation, essential insurance and required debt payments.
What counts as a want?
Wants are discretionary expenses that improve your lifestyle but are not essential, such as entertainment, dining out, hobbies and non-essential shopping.
Does the 20% include investments?
Yes. The savings and financial-goals category can include savings and investments, depending on your circumstances. It can also include additional debt repayment.
What if I cannot save 20% of my income?
That’s okay. Start with an amount you can realistically save and increase it gradually when your financial situation allows.
Is the 50/30/20 rule good for beginners?
It can be a useful starting framework because it is simple and easy to understand. Beginners should treat it as a guide rather than a strict requirement.
Key Takeaways
The 50/30/20 budget rule provides a simple way to think about your monthly income:
- 50% → Needs
- 30% → Wants
- 20% → Savings and debt repayment
But remember that these percentages are guidelines, not fixed rules.
If your financial circumstances don’t allow a 50/30/20 split, create a budget that reflects your actual income, expenses and goals.
The most important thing is to understand where your money goes, spend intentionally, save consistently and review your budget regularly.
Sources & References
For financial education and investor information, readers can refer to authoritative Indian sources such as:
- Reserve Bank of India — Financial Education
- Securities and Exchange Board of India — Investor Education
- Income Tax Department — Taxpayer Services
About This Article
Written by: NiveshPedia Editorial Team
Published: September 2026
Last Updated: September 2026
Disclaimer
The information provided in this article is intended for general educational and informational purposes only. It does not constitute personalized financial, investment, tax or legal advice. Financial decisions depend on individual circumstances, goals and risk tolerance. Please conduct your own research and consider consulting a qualified professional before making important financial decisions.